Prop 37: No
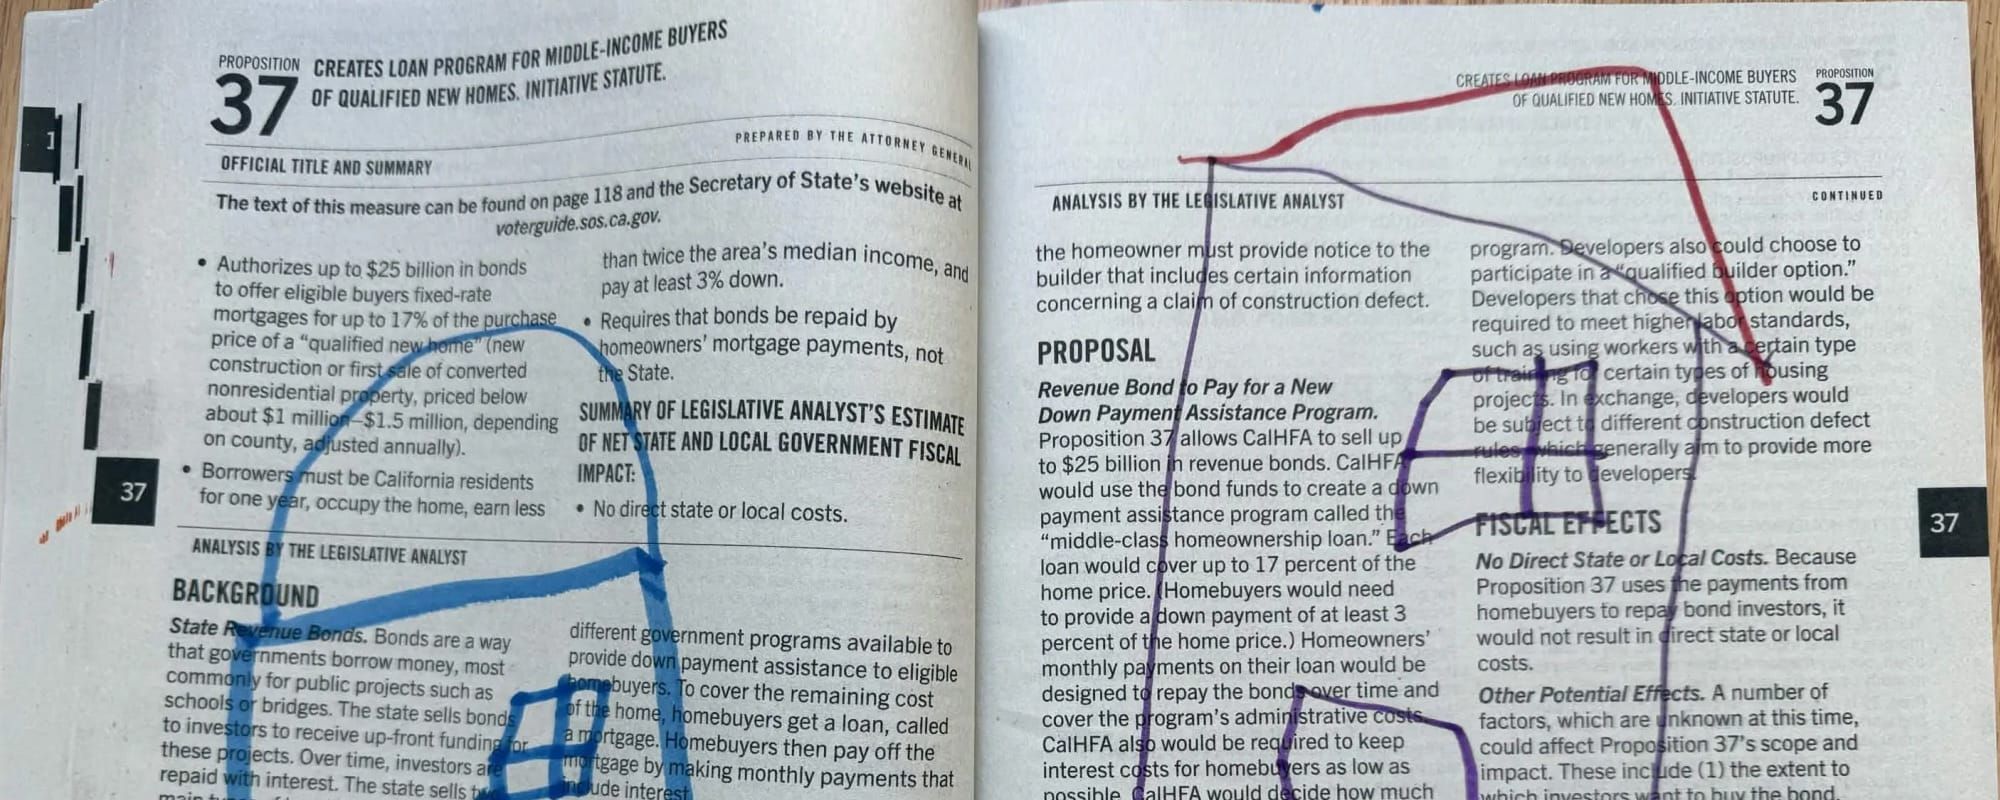
“Second Mortgage Homebuyer Program and Revenue Bond Initiative”
The state’s Official Voter Guide has a big old “NO ARGUMENT AGAINST PROPOSITION 37 WAS SUBMITTED” and everybody loves to borrow to buy a house, so it’s probably going to pass because of that. But for once, the Reform California weirdos are right, kind of, though you’d do better to read the League of Women Voters’ opposition position if you want a voter guide’s take that isn’t ours (you don’t, though).
The theory here is that the state will borrow up to $25 billion from private lenders, then offer this money as fixed-rate second mortgages to homeowners who can get first mortgages to purchase a house but cannot afford to cover the down payment. It will thus benefit a pretty narrow group of people: people with enough future income to get a mortgage but not enough savings to buy a home, and it will do so by allowing those people to increase their monthly payments for houses in the future to get around the fact they can’t afford a down payment now. Are such individuals sympathetic in a state where “starter homes” go for a cool million dollars? Sure. Should we authorize the state to borrow $25 billion to facilitate this increase in debt? Absolutely the fuck not. This idea—offering more and more debt to facilitate the purchase of houses that have ever higher prices due to a society-wide dependence on assessed house values as the sole source of wealth for the middle chunk of wage earners—should sound familiar, because it is, in rough outline, a major contributing factor to the mortgage foreclosure crisis of 2008 and the Great Recession. Let’s not do that again!
 Oakland Review of Books
This measure doubles down on basically everything that’s wrong with California housing policy. It privileges homeownership as the only means of securing long-term economic viability in a society without a sufficient social safety net (why a down payment subsidy rather than a rent subsidy?); purports to address affordability by pouring more money into housing, thereby intensifying the commodification of housing (if everyone can access an additional 17 percent for down payments, down payments—and housing prices—will go up); and exalts homeownership itself as a social good at the expense of taxpayers as a whole (even if it’s just the time and money spent passing the damn thing and administering the program). It’s increasing the speed on our housing price treadmill, while not fundamentally altering the dynamics that make Californians housing insecure. Vote no, however futilely.
Find more of our voting guide here.